Fed Hikes in 12-0 Vote, Commits to Inflation Fight
The Federal Reserve delivered its first hike in more than three years Wednesday, lifting rates 25 basis points in a unanimous 12-0 vote as policymakers wrestles with inflation stubbornly above their 2% target.
Major indexes initially rose on the news, while Treasury yields flattened with the 10-year Treasury yield near 19-year highs. But after Fed Chairman Kevin Warsh spoke at his press conference, major indexes surrendered earlier gains and then plunged with half an hour left in the session.
In addition, 16 of 19 members of the Federal Open Market Committee (FOMC) expect at least one more rate hike this year, according to the Fed's "dot plot" of projections. Warsh didn't provide a dot. The Fed's target range is now 3.75% to 4%, up from 3.5% to 3.75% where it had been since a cut last December.
The average projection for rates at the end of this year rose to 4.1% from the June projection of 3.8%, while next year's projection was 4.1%, up from 3.6%. Eight policymakers projected the possibility of two more hikes between now and the end of next year.
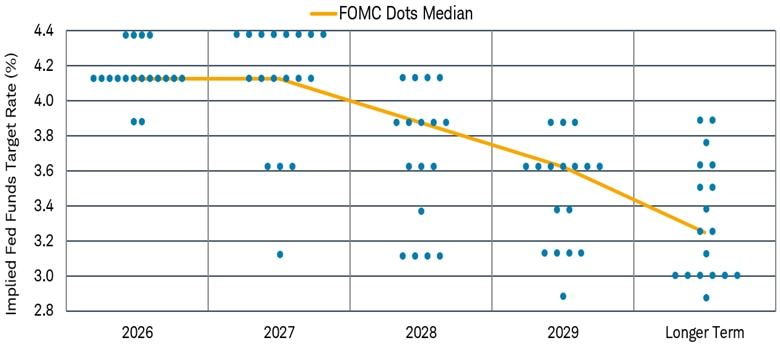
Source: Bloomberg, Federal Reserve.
Note: FOMC "dot plot" as of 9/16/2026.
This isn't likely to be "one-and-done" for hikes but also probably won't be the start of an extended hiking cycle. Only eight dots project another 25 basis points in 2027. This implies that there will likely be a second rate hike this year, but another hike next year will depend on the pace and outlook of inflation moving back towards 2%.
In his press conference, Warsh said, "Inflation is too high and has been for too long." He said the predominant focus is on the price stability side of the Fed's dual mandate, and that the decision to hike was "serious and responsible." Recent inflation readings didn't suggest to Warsh that underlying trends have meaningfully improved.
The economy's continued resilience and bumpy geopolitics since the July meeting helped determine the Fed's decision to "remove a dose of accommodation," as Warsh described the hike.
He declined to say what his "neutral rate" might be and noted that strong economic growth and competition for debt amid the AI buildout help explain the rise in Treasury yields.
Warsh's words failed to soothe. As he finished his press conference, the 10-year yield climbed back to 5% after falling below 4.95% earlier in the day. Thirty minutes after the press conference ended, the S&P 500 Index was down 1% to new six-week lows just above 7,500. Every S&P 500 sector was red.
The road to a rate hike
Several recent developments drove the Fed's decision. Warsh's Jackson Hole speech late last month was the big change when he acknowledged that despite the relatively good summer inflation prints, he saw strong underlying trends in inflation. He made clear then he wasn't seeing enough progress and that 2% is the Fed's target for the Personal Consumption Expenditures (PCE) price index.
He also said then that aside from housing and agriculture, he'd be hard pressed to describe financial conditions as restrictive, which he repeated Wednesday. That set the stage, signaling that unless significant improvements occurred in a short time frame, a hike seemed likely.
Last week, the monthly core Consumer Price Index, which excludes volatile food and energy prices, came in stronger than expected. The 0.3% rise was higher than the Fed wanted to see and that was likely the nail in the coffin.
More importantly, the economy continues to grow, the labor market is stable, and the unemployment rate has been gradually declining. If the labor market had been weakening and the August jobs report hadn't been strong, then it might be a different story.
Instead, August jobs growth announced early this month was a solid 162,000. That reading was accompanied by upward adjustments to June and July growth, lifting the three-month average above 70,000.
The Fed rarely hikes or cuts a single time. An exception was in March 1997 when the Fed hiked just once. The next move was a cut in September 1998. That was the last true "one and done" move upward.
From an economic perspective, 25 basis points isn't going to do too much, but sends a message. A cumulative rise of 50 basis points might curb spending enough to slow inflation growth, and that's what the dot plot suggests the Fed might move toward.
Market reaction
"Inflation remains elevated," the Fed's statement said. "Today's policy action will support a timelier return to the Committee's 2 percent goal. The Committee will deliver price stability."
The Fed's decision was well telegraphed by CME futures trading, which pegged chances of a 25-basis point hike at 92% this morning heading into the meeting.
Immediately after Warsh's press conference, the market saw a 49% chance of a hike in October, according to the CME FedWatch Tool, compared with 40% on Wednesday morning.
The chances of at least one more hike this year stood at 87% after Warsh's remarks, compared with 77% Wednesday morning. Chances of two more hikes this year were 37%, compared with 27% earlier in the day.
Fed updates projections
The Fed's so-called "dot plot" of economic projections showed 16 of 18 members projecting at least one more rate hike this year.
At the June meeting, nine members were projecting at least one hike in 2026, while eight others projected rates to remain unchanged. There was still one dot in June projecting a rate cut this year. That was not the case this time. Four of the policymakers expect two more hikes this year.
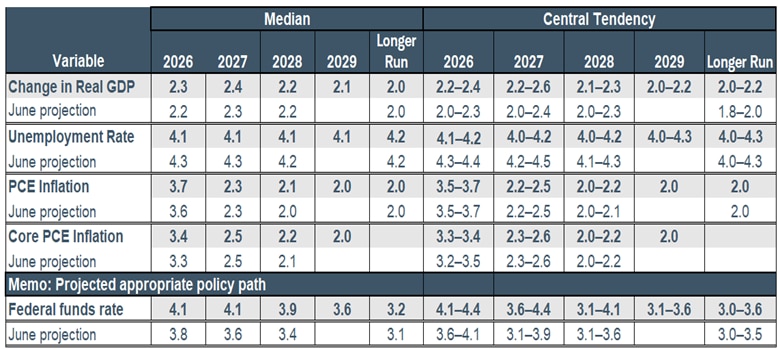
Source: Federal Reserve Board, 9/16/2026.
Notes: For each period, the median is the middle projection when the projections are arranged from lowest to highest. When the number of projections is even, the median is the average of the two middle projections. The central tendency excludes the three highest and three lowest projections for each variable in each year. The range for a variable in a given year includes all participants' projections, from lowest to highest, for that variable in that year. Longer Run projections for Core PCE are not collected.
The dot plot for 2027 showed all but four voters expecting higher rates than now by the end of next year. More expected two hikes than expected one. Three expected one cut and one expected several cuts by year-end 2027. The dot plot isn't an official projection, only a survey of each member.
The Fed pegged 2026 headline and core PCE price growth at 3.7% and 3.4%, respectively, compared with June's estimates of 3.6% and 3.3%. For 2027, it sees headline and core PCE prices up 2.3% and 2.5%, unchanged from June's estimates. Policymakers don't see a return to 2% inflation until 2029.
The gross domestic product (GDP) projection was revised higher this year from 2.2 to 2.3% and from 2.3% to 2.4% in 2027. Beyond 2028, projections for GDP were unchanged.
Projections for the unemployment rate were revised lower from 4.3% to 4.1% in both 2026 and 2027.
Summing it up, Kevin Warsh laid out a relatively hawkish path forward. He made it clear that the underlying inflation trends have not meaningfully improved, and by stating that the rate hike "removed a dose of accommodation" suggests that he does not see policy as particularly restrictive. As the dot plot suggests, there’s likely more work to be done to get inflation down in a timely manner.