Looking to the Futures
Oats Futures stabilize after front-month contracts roll
Canadian dollar futures (/6C, currently scheduled for December delivery) have dropped sharply since the beginning of November. The Canadian dollar had rallied from a mid-October low of 0.7022 up to 0.718 to end the month. Since then, economic data and oil prices and inventories have put pressure on CAD.
While U.S. elections dominated the news at the start of the month, the big move in the Canadian dollar came after employment data released on Friday, November 6. Canadian employment change for October came in at -4.7k against expectations of a 14.6k gain. It was the third consecutive month of job losses, with a combined total of -114.7k. The unemployment rate of 6.7% was also higher than the forecast of 6.5%. In contrast, U.S. employment numbers for October all beat expectations. Earnings increased 0.4% month-over-month, 0.1% ahead of forecasts. Non-farm payrolls grew by 165k, topping expectations by 100k, and the unemployment rate dropped by 0.1% to 4.1% while the forecast had been for no change.
Last week brought more bad news for the Loonie. U.S. consumer inflation was hotter than expected, with Core CPI rising 0.3% for the month and CPI gaining 0.4%. Both numbers topped forecasts by 0.1%. This week saw more of the same story of divergence. Monday’s Canadian inflation numbers were lower than expected. CPI rose 0.2% monthly, 0.1% below expectations. Statistics Canada’s Trimmed CPI, similar to our Core CPI in excluding the most volatile items, rose 1.8% for the year against forecasts of a 1.9% increase. Yesterday, U.S. retail sales grew 0.2%, doubling the forecast, while core retail sales (ex-autos) rose 0.6%, topping forecasts for a 0.4% rise.
The differing economic news could lead to a wider gap in interest rates between the two countries. The Bank of Canada’s policy interest rate is now at 2.50% following a 25 basis-point hike in late October, the first hike in over three years and the first change in rates in a year. In the states, the current Fed Funds rate target is 3.75%-4.00% following a hike in September, and the CME FedWatch Tool shows rates traders are unanimous in expecting another increase on December 9. There is a 94% consensus for a 25 basis-point increase, though some hawks are expecting half a point.
In addition to the economic data, energy prices have added another headwind. Canada is a major oil exporter, and the currency has historically been sensitive to energy prices. West Texas Intermediate crude oil futures (/CL) have dropped between 10% and 15% across all 2028 expirations since the end of October. Looking at the bilateral energy trade, the U.S. is the recipient of around 90% of Canadian crude exports. Adding to the bearish news, U.S. commercial crude oil inventories have topped expectations for both of the November releases so far. The first week saw a decrease of -0.9Mbbl versus expectations of a -1.7Mbbl draw. The report last week showed a surprising 4.7Mbbl build against forecasts of a -0.6Mbbl draw. That made for the largest increase in three months, although total stocks of 414.4Mbbl were below the five-year average. The Strategic Petroleum Reserve saw a decrease of -2.65Mbbl to 279.54Mbbl, a new 40+ year low.
EIA crude oil inventories come out today at 10:30am ET, followed by FOMC minutes at 2:00pm ET. Looking ahead to a short week, we will have Core PCE and Preliminary Third Quarter GDP numbers on Wednesday. The following Monday will see Canadian GDP for the month of September. If Canadian GDP accelerates or domestic inflation moderates, we could see some moderation in exchange rates. However, if the U.S. economy continues to grow faster, it could be the worst of times for the Loonie.
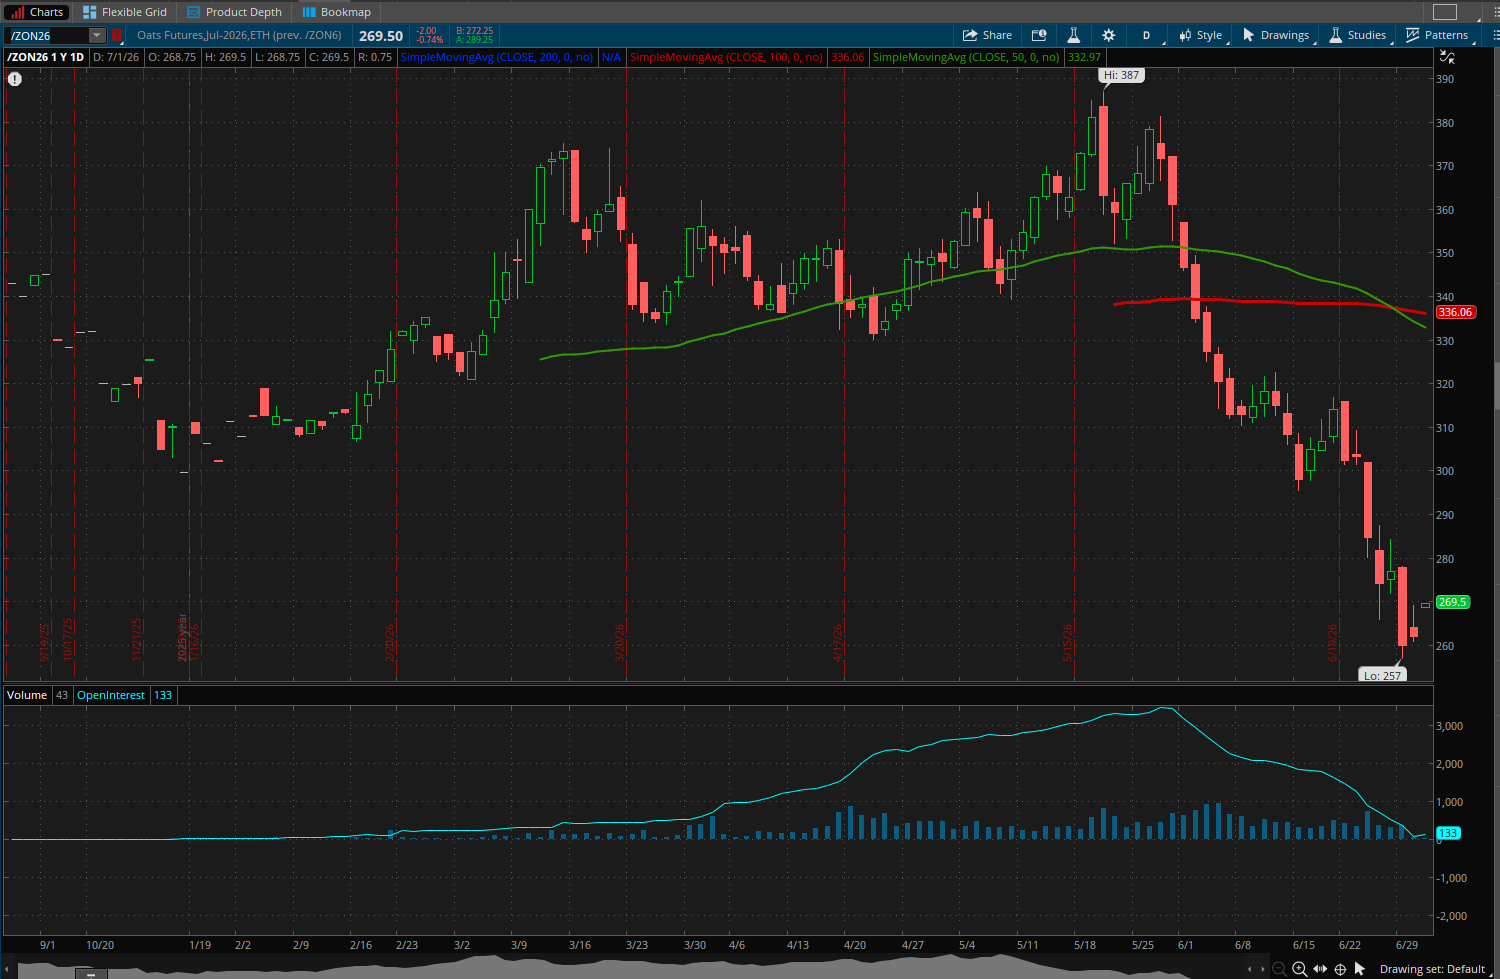
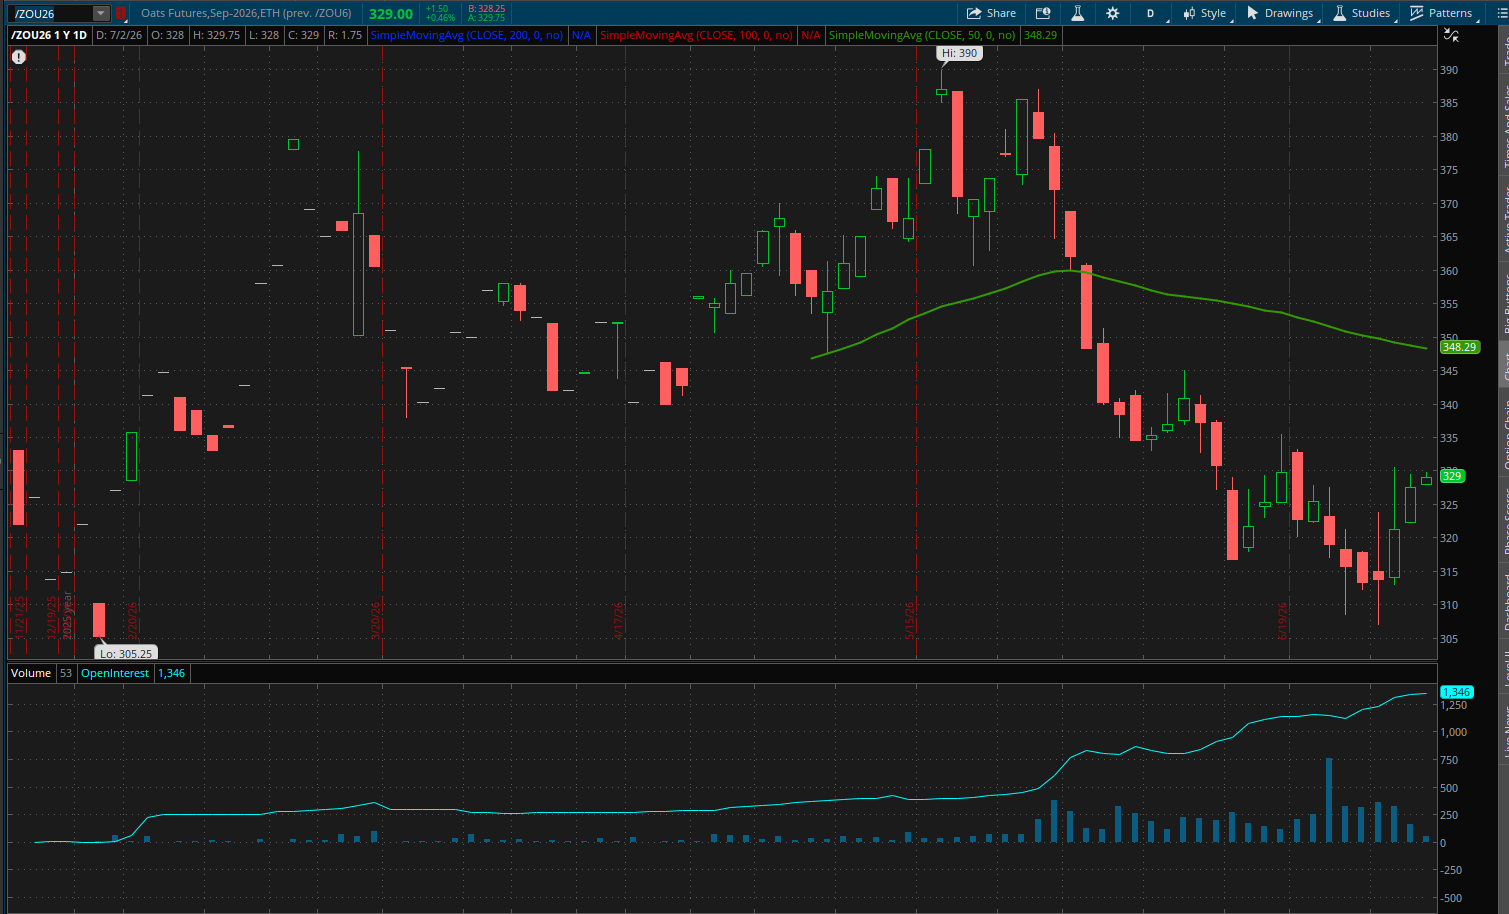
Light Sweet Crude Oil futures (/CL) have traded in a wide range since June 30, moving between 67.04 and 93.50. Prices have since pulled back and are trading below the 9-day, 50-day, and 100-day simple moving averages (SMA), while remaining above the 200-day (SMA), which recently acted as support after crude briefly moved below it and reached a low of 67.04 on July 2. From a short-term trend perspective, the 9-day (SMA) crossed above the 50-day simple moving average on July 27, which may be viewed as a bullish technical development. However, the 20-day simple moving average and 21-day exponential moving average remain below the 50-day (SMA), suggesting the broader technical picture remains mixed. Volatility has eased from mid-month levels, falling from a high near 175% to roughly 69%. Momentum has also cooled, with the relative strength index declining from near 70 to 52.6. With the RSI only slightly above 50, momentum appears more neutral and may suggest crude is beginning to stabilize.
New Products
New futures products are available to trade with a futures-approved account on all thinkorswim platforms:
- Ripple (/XRP)
- Micro Ripple (/MXP)
- 100 OZ Silver (/SIC)
- 1 OZ Gold (/1OZ)
- Solana (/SOL)
- Micro Solana (/MSL)
Visit the Schwab.com Futures Markets page to explore the wide variety of futures contracts available for trading through Charles Schwab Futures and Forex LLC.